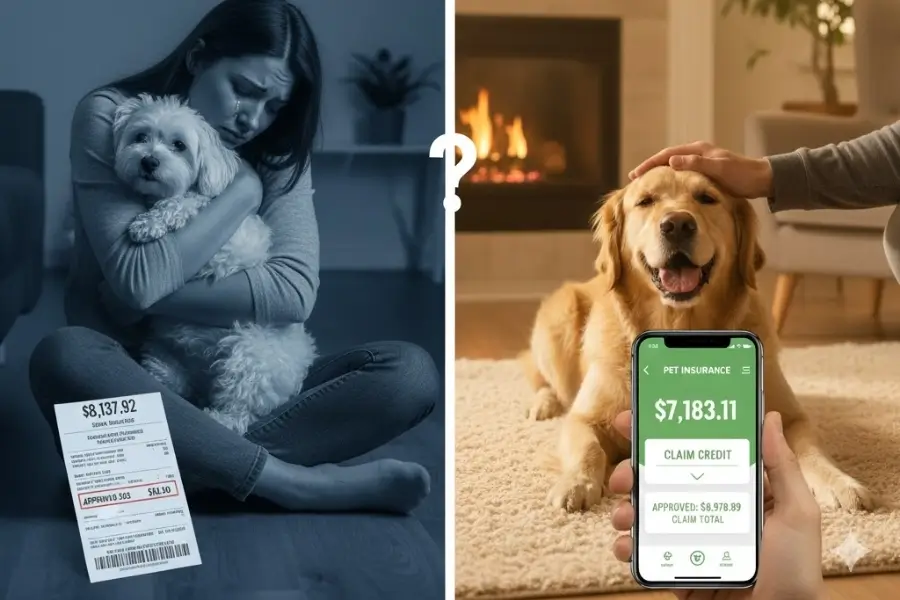
Pet insurance is one of those decisions that is genuinely hard to make well, because the thing you are buying is protection against something that may never happen.
Here is how the maths actually works, what the policies really cover, and the honest answer about who should buy it.
What vet care costs now
Veterinary medicine can treat a great deal that was untreatable twenty years ago, and the bills reflect that. Rough ranges, which vary a lot by region:
- Emergency visit: 200 to 1,000 dollars and up.
- Broken bone repair: 2,000 to 5,000 dollars and up.
- Cruciate ligament surgery: 3,000 to 6,000 dollars and up.
- Cancer treatment: 5,000 to 20,000 dollars and up.
- Removing something swallowed: 1,500 to 4,000 dollars.
- Managing a chronic illness such as diabetes or kidney disease: hundreds to thousands every year, indefinitely.
Most pets will meet at least one of these in a lifetime. The question is not whether a large bill arrives but whether you would rather pay it in one piece or in instalments beforehand.
How the policies work
Unlike human health cover, pet insurance is almost always reimbursement. You pay the vet, then claim it back. That matters, because it means insurance does not remove the need for money available today.
- Premium: what you pay monthly or annually.
- Deductible: what you cover yourself before anything is reimbursed, either per year or per condition.
- Reimbursement level: the share they pay after the deductible, commonly 70, 80 or 90 percent.
- Annual limit: the ceiling on what they will pay in a policy year.
- Waiting period: the stretch after you buy during which nothing is covered.
- Pre-existing conditions: anything that appeared, or showed symptoms, before the policy or during the waiting period. Almost never covered.
The types of cover
- Accident only. Injuries, not illness. The cheapest by a distance.
- Accident and illness. The usual choice, covering injuries, common illnesses and serious conditions including surgery.
- Wellness add-ons. Routine care such as vaccinations, check-ups and dental cleaning, bolted onto a main policy. These rarely save money, because you are prepaying predictable costs with an administration fee on top.
What it costs
Premiums move with breed, age, where you live and the plan you pick. Pedigrees with known genetic conditions cost more. Age is the big one, and premiums keep rising as the animal gets older.
Very broadly, 30 to 70 dollars a month for a dog and 15 to 40 for a cat. Treat that as a starting point and get several real quotes, because the spread between providers for the same animal is wide.
The case for
- It removes the worst decision in pet ownership, which is choosing treatment on the basis of what you can raise this week.
- You say yes to diagnostics and referrals you would otherwise hesitate over, and hesitation costs outcomes.
- A predictable monthly figure is easier to absorb than an unpredictable four-figure one.
- If a chronic condition appears early, a policy bought before it can carry years of treatment.
The case against
- Plenty of pets stay healthy, and those owners pay for years and claim nothing.
- Pre-existing conditions are excluded, which is the limitation that catches most people out and the reason cover is worth far less once a pet is middle-aged.
- Waiting periods mean cover is not immediate.
- You still pay up front and wait to be reimbursed.
- The policies are genuinely hard to compare, and the differences that matter are in the exclusions rather than the headline price.
So is it worth it
It is worth it if a sudden four-figure bill would be a real problem, and it is most worth it bought while the animal is young and has no history, which is exactly when it feels least necessary.
If you have savings you would genuinely spend on the animal without hesitating, a dedicated account works out cheaper over most pets’ lives and has no exclusions. That is a real alternative rather than a way of avoiding the decision, but only if the money actually goes in every month and is left alone.
What does not work is intending to sort it out later. Later is after the diagnosis, and by then the condition you want covered is the one thing no policy will touch.

0 Comments